There isn’t one retirement savings amount that works for every federal employee. The amount you may need can depend on your expected retirement age, lifestyle, spending needs, FERS or CSRS benefits, TSP balance, Social Security, other savings, taxes, and how long your retirement may last.
Rather than focusing on a single dollar amount, it can be helpful to look at how your potential retirement income sources and savings may work together.
Retirement savings are only one part of the picture for federal employees. Depending on your retirement system and individual circumstances, your potential retirement income may include:
Will my expected retirement income and assets support the lifestyle I want throughout retirement?
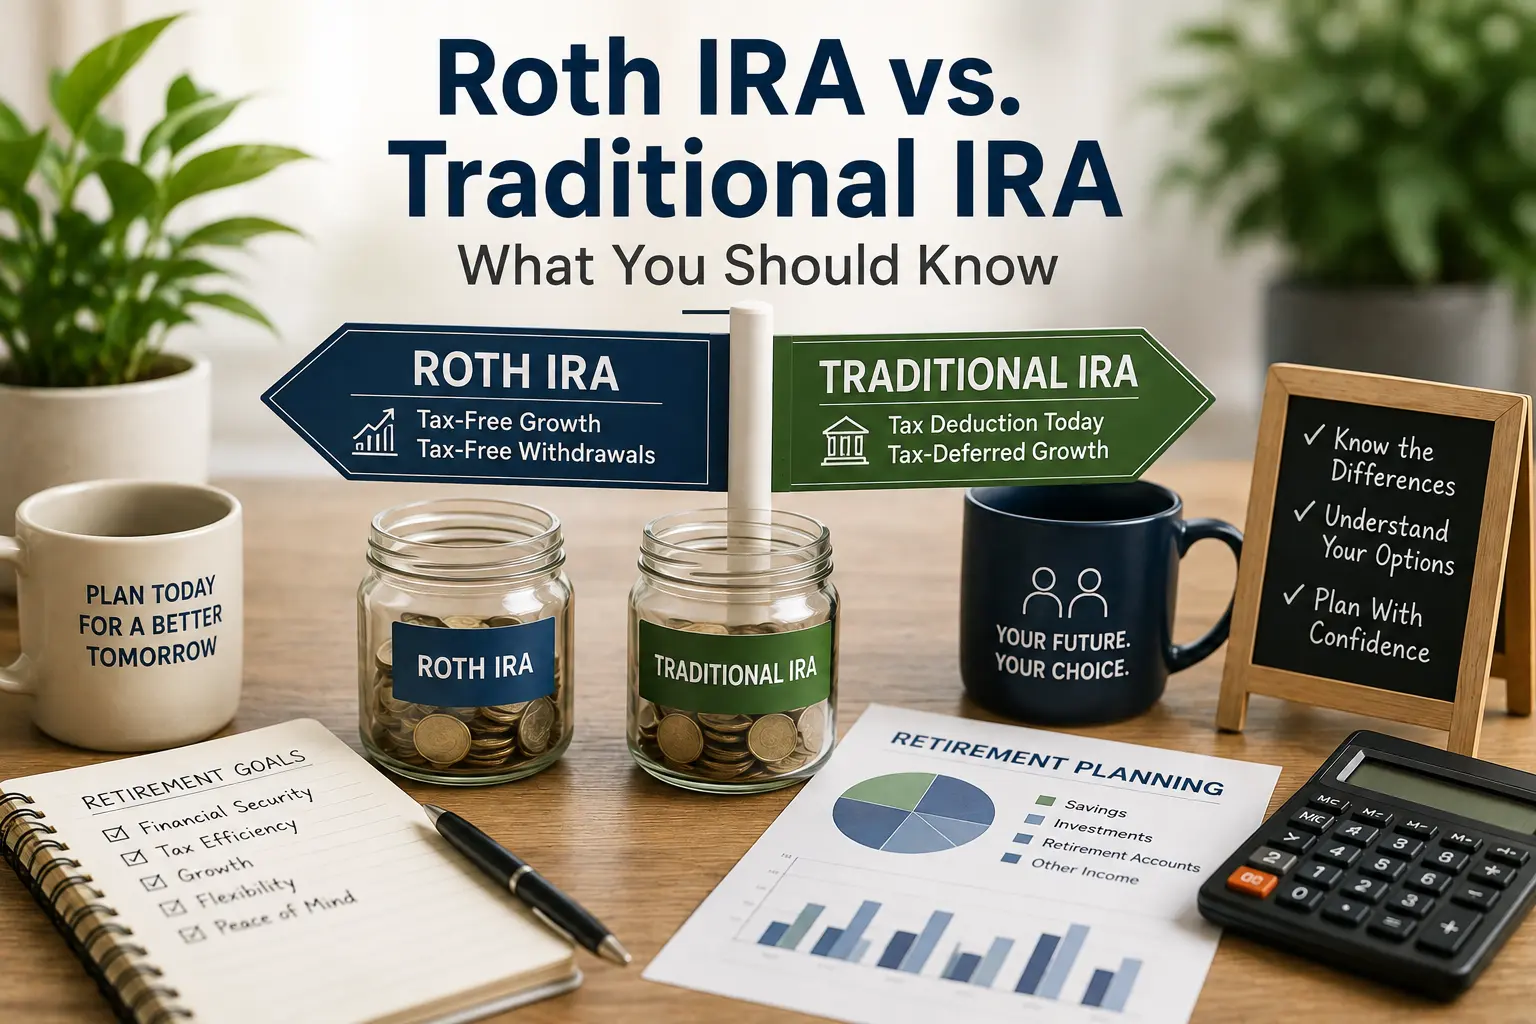
Traditional IRA
Roth IRA
The TSP is another important retirement savings resource for eligible federal employees. Your TSP balance, contribution history, investment allocation, withdrawal approach, and other circumstances may all be relevant when evaluating your overall retirement income picture.
Healthcare can become an important part of retirement planning. Federal employees may also need to consider how their Federal Employees Health Benefits (FEHB) coverage, Medicare, supplemental coverage, prescription medications, dental care, vision care, and potential long-term care costs could affect retirement expenses.
Once you’ve estimated your expenses and identified your retirement income sources and assets, you can begin thinking about how those resources may work together.
Questions to consider include:
These questions don’t have the same answer for everyone. Your retirement strategy may need to change as your income, expenses, investments, tax situation, and personal circumstances change.
There is no universal savings balance that guarantees retirement readiness.
Instead, consider your retirement picture as a combination of:
Your expenses + FERS or CSRS benefits + TSP + Social Security + other savings + retirement timeline + taxes + personal goals
Looking at these factors together can provide a more useful framework for evaluating whether your current savings and potential retirement income may support your expected needs.
There isn’t a single retirement savings number that applies to every federal employee.
Your retirement readiness may depend on how your FERS or CSRS benefits, TSP, Social Security, other retirement accounts, savings, taxes, healthcare expenses, and expected spending fit together.
Rather than relying on a general savings target, understanding your individual income sources and projected expenses can help you identify the areas that may require additional planning or review.
Federal retirement planning involves more than reaching a specific savings balance. Your federal retirement benefits, TSP, Social Security, other retirement accounts, taxes, healthcare costs, and expected expenses may all be relevant to your overall financial picture.
Federal Employee Advisor Network can help connect federal employees and retirees with independent, licensed financial professionals who may be familiar with federal retirement planning considerations.
The professional you are connected with can discuss your individual circumstances, goals, and available options directly with you.
Federal Employee Advisor Network is a connection service and does not itself provide individualized investment, tax, legal, or retirement advice. Information on this website is provided for general educational purposes and should not be considered personalized financial advice, a recommendation, or a guarantee of results.
Professionals connected through the network are independent from Federal Employee Advisor Network and are responsible for the services and advice they provide. Before engaging a professional, individuals should review the professional’s qualifications, services, fees, licenses, registrations, and applicable disclosures.
Tax laws, retirement rules, Social Security rules, and federal benefits can change. Information presented on this website may not apply to every individual or reflect the most recent applicable rules. Consider consulting appropriately qualified professionals regarding your specific circumstances.