Federal employees may have several potential sources of retirement income, including FERS or CSRS benefits, the Thrift Savings Plan (TSP), and Social Security. Understanding when to claim Social Security can help you evaluate how this income source may fit with your other retirement resources.
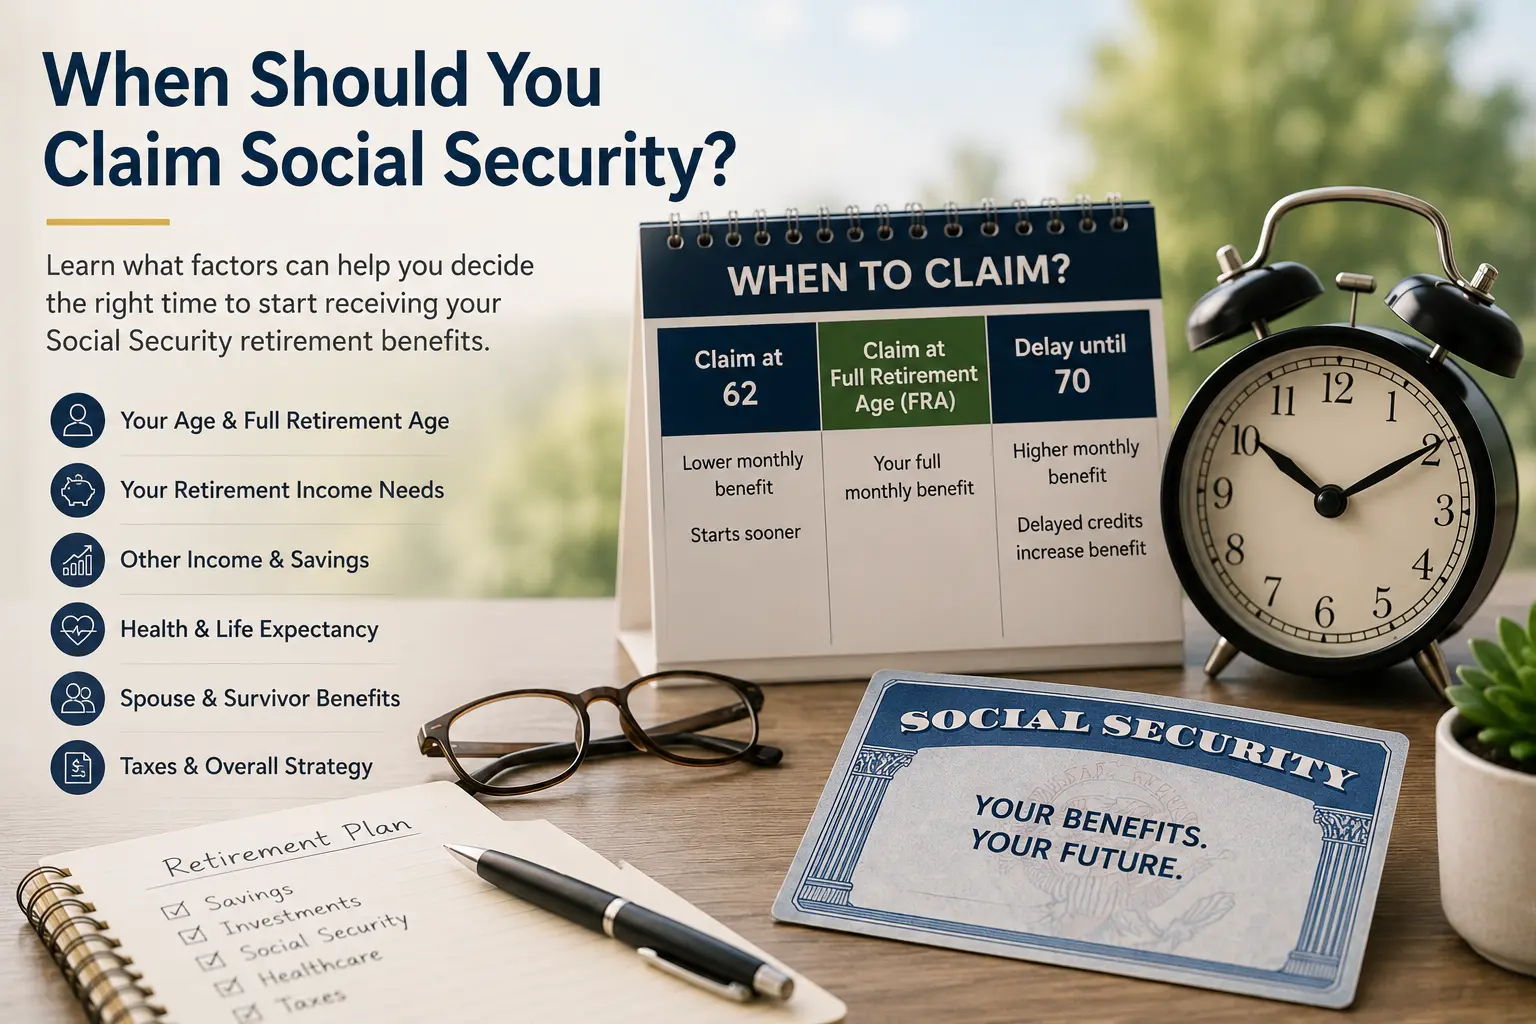
You can generally begin receiving Social Security retirement benefits at age 62. However, claiming before your Full Retirement Age (FRA) generally results in a reduced monthly benefit, while delaying benefits beyond FRA can increase your monthly benefit until age 70.
For federal employees, Social Security is one part of a broader retirement picture. Factors such as federal retirement benefits, TSP savings, taxes, health, spouse or survivor benefits, and retirement income needs may all be relevant when evaluating your options.
Starting Social Security at age 62 can provide retirement income earlier.
This may be worth considering for people who:
However, claiming Social Security before Full Retirement Age generally results in a permanently reduced monthly benefit compared with the full retirement benefit available at FRA.
Your individual benefit amount depends on your earnings history, claiming age, and applicable Social Security rules.
Your Full Retirement Age (FRA) depends on your year of birth.
For people born in 1960 or later, the current Full Retirement Age is 67.
Claiming at FRA generally provides your full scheduled retirement benefit, rather than the reduction that can apply when benefits are claimed earlier.
For some individuals, waiting until FRA may be one factor to consider when balancing the timing of Social Security income with other retirement resources.
If you do not need Social Security income immediately, delaying retirement benefits beyond Full Retirement Age can increase your monthly benefit.
For eligible individuals, delayed retirement credits generally increase benefits until age 70. After age 70, there is generally no additional increase for continuing to delay retirement benefits.
For example, under the current Social Security schedule, someone whose Full Retirement Age is 67 can receive 100% of their full retirement benefit at FRA. Waiting until age 70 can increase the benefit to 124%.
The actual benefit amount and applicable rules depend on your individual circumstances and Social Security record.
Social Security generally should not be evaluated in isolation.
Federal employees may also have:
Depending on your circumstances, other retirement resources may provide income while you delay Social Security. This is one consideration when evaluating whether delaying benefits fits within your broader retirement income strategy.
For FERS employees, Social Security is one component of the retirement system and may work alongside a FERS pension and TSP savings.
CSRS employees may have different retirement income considerations, making it important to evaluate their Social Security situation within the context of their overall benefits and circumstances.
Personal circumstances can also be relevant when evaluating when to claim Social Security.
For someone who expects a longer retirement, a higher monthly benefit resulting from delayed claiming may become increasingly important over time.
For someone with different health or longevity considerations, the factors involved may look different.
There is no single claiming age that is appropriate for everyone. Your circumstances, goals, and other retirement resources can all affect the decision.
Married couples may also want to consider how each spouse’s Social Security claiming decision could affect their overall household retirement income.
Spousal and survivor benefits may be relevant, depending on your circumstances.
The timing of one spouse’s benefits can also affect the household’s income strategy, so couples may benefit from evaluating both individuals’ Social Security records and retirement resources together.
Continuing to work can affect Social Security benefits in several ways.
Social Security generally calculates retirement benefits using your highest 35 years of earnings. If you have fewer than 35 years of earnings, years without earnings may be included in the calculation.
If you continue working after beginning Social Security before Full Retirement Age, the Social Security earnings test may also affect your benefits in certain circumstances.
Because the rules can vary based on your age and earnings, review the current Social Security Administration rules when evaluating your situation.
Social Security and Medicare are separate programs, so delaying Social Security does not necessarily mean you should delay Medicare enrollment.
If you plan to delay Social Security beyond age 65, make sure you understand Medicare enrollment requirements and how your federal health coverage may interact with Medicare.
Federal employees should consider their Federal Employees Health Benefits (FEHB) coverage and applicable Medicare rules when planning for healthcare costs in retirement.
The appropriate Social Security claiming age depends on your individual circumstances.
Factors that may be relevant include:
Your age + health + spouse + income needs + retirement savings + taxes + longevity + other income sources
Looking at these factors together may provide a more complete picture than focusing on age alone.
Social Security can be an important source of retirement income, but deciding when to claim benefits is an individual financial decision.
Starting at age 62 may provide income sooner, while waiting until Full Retirement Age or later generally results in a higher monthly benefit. For eligible individuals, delayed retirement credits generally continue until age 70.
For federal employees, the decision may also involve FERS or CSRS benefits, TSP savings, other retirement accounts, taxes, healthcare considerations, spouse or survivor benefits, and personal income needs.
Understanding these factors can help you identify the questions you may want to discuss with a qualified professional before making a Social Security claiming decision.
Social Security is only one part of a federal employee’s retirement income picture. FERS or CSRS benefits, TSP savings, other retirement accounts, taxes, healthcare costs, and personal income needs may all be relevant when evaluating retirement planning options.
Federal Employee Advisor Network can help connect federal employees and retirees with independent, licensed financial professionals who may be familiar with federal retirement planning considerations.
The professional you are connected with can discuss your individual circumstances and help you understand the factors that may be relevant to your retirement planning decisions.
Federal Employee Advisor Network is a connection service and does not itself provide individualized investment, tax, legal, Social Security, or retirement advice. Information on this website is provided for general educational purposes and should not be considered personalized financial advice, a recommendation, or a guarantee of results.
Professionals connected through the network are independent from Federal Employee Advisor Network and are responsible for the services and advice they provide. Before engaging a professional, individuals should review the professional’s qualifications, services, fees, licenses, registrations, and applicable disclosures.
Social Security, Medicare, tax, and retirement rules can change. Information presented on this website may not reflect every individual’s circumstances or the most recent applicable rules. Consider consulting the appropriate government resources and qualified professionals regarding your specific situation.